Why Three Ten-Year-Old Turbines in Poland Are Priced at $2 Million a Megawatt
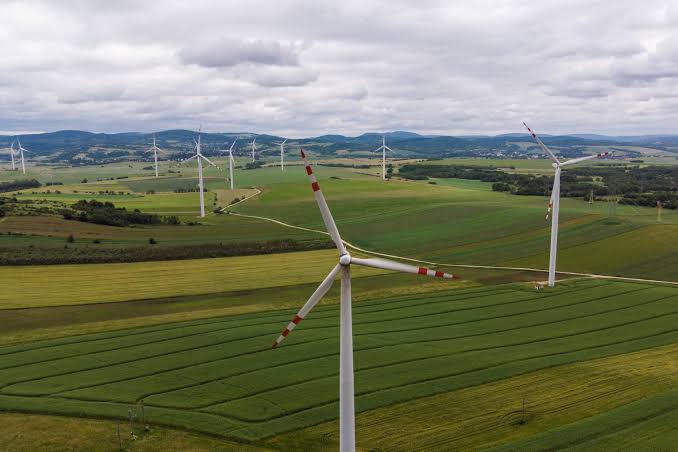
Airengy is paying around EUR 13.5 million for three wind turbines in Poland that have been spinning since 2015. That works out at $2.00 million for every megawatt of installed capacity. Two months ago PPC Group paid roughly half that per megawatt for 277 MW of operating Polish wind and solar. The turbines are not what is being priced here.
Key takeaways
- Airengy has entered an agreement of principles to acquire the 7.84 MW FLUX wind project in Poland from VH Invest GmbH for approximately EUR 13.5 million, equivalent to $15.71 million or $2.00 million per MW.
- The project comprises three GE wind turbines that entered commercial operation in December 2015 and June 2016, and its electricity is sold on the Polish free market rather than under a long-term contract.
- Airengy estimates average full-year revenue of approximately NIS 8.87 million ($2.93 million) and average full-year EBITDA of approximately NIS 5.32 million ($1.76 million), which places the consideration at roughly 8.9 times EBITDA and 5.4 times revenue.
- The sellers have granted Airengy a two-month exclusivity period while legal, engineering and financial due diligence is completed, with the transaction expected to close by 31 December 2026. Enerdatics identifies VH Invest as the seller through its ownership of WINDCLUB, LLC, the special purpose vehicle that owns the project.
- Enerdatics records 21 Polish wind transactions since the start of 2024, of which 11 carry a disclosed value. Among operating asset deals the priced range runs from $1.04 million per MW to $2.75 million per MW.
What is Airengy actually buying for $2 million a megawatt?
Earnings, and a specific quantity of them. Airengy has published its own estimate of what the asset produces, at roughly $2.93 million of average full-year revenue and roughly $1.76 million of average full-year EBITDA. Divide the consideration by that EBITDA figure and the price resolves to about 8.9 times, or about 5.4 times revenue. Those are the numbers that govern the deal.
The reason a small, decade-old asset can carry that multiple is the route to market. Electricity from the project is sold on the free market, which means output is priced at the prevailing wholesale rate rather than fixed under a contract for difference or a long-term power purchase agreement. A merchant asset of this kind captures whatever Polish wholesale prices do, in both directions. Buyers of contracted assets pay for certainty. A buyer of a merchant asset is paying for the cash it currently throws off and accepting the risk that the figure moves.
Is $2 million per megawatt expensive for Polish wind?
Less than it looks. The comparable set is small but it brackets this deal on both sides. In July 2026 PPC Group agreed to pay $287.16 million for a 277.3 MW operating solar and wind portfolio sold by EDP Renewables, or $1.04 million per MW. In April 2025 Enea acquired the 83.2 MW Pelplin wind farm from Greenvolt for $202.11 million, or $2.43 million per MW. A month earlier Enea paid $236.81 million for an 86.15 MW wind and solar portfolio from European Energy, or $2.75 million per MW. Against those three prints, $2.00 million per MW sits in the middle.
The spread within a single market and a single technology is the thing worth noticing. Development-stage Polish wind changes hands far lower, with ZE PAK and Cyfrowy Polsat paying $0.24 million per MW for the roughly 500 MW Opole project in June 2024 and Unimot paying $0.39 million per MW for the 34 MW Gostynin project in June 2026. An unbuilt megawatt in Poland trades at a fifth to a sixth of an operating one, because what is being sold is a permit and a grid position rather than a revenue stream. Comparing an operating asset against that pool is what makes $2.00 million per MW look rich.
Why does an agreement of principles change how this should be read?
Because it is not a signed purchase agreement. An agreement of principles sets out the terms the parties intend to document, without binding either of them to complete on those terms. Airengy has been granted a two-month exclusivity period, meaning the sellers cannot negotiate with anyone else during that window, and it is still working through legal, engineering and financial due diligence. Price, and in some cases the deal itself, remains contingent on what that work finds.
That matters more for a merchant asset than a contracted one. Due diligence on a project with a twenty-year offtake contract largely confirms the contract. Due diligence here has to test the generation record, the condition of turbines that have run for a decade, and the operating cost base that turns revenue into the EBITDA the price rests on. The estimate is Airengy's own. Two months of engineering review is what stands between it and a binding number.
Enerdatics records this as the smallest Polish wind transaction on its books since the start of 2024. The next smallest is the 30 MW Kamionka farm that ENGIE bought from BayWa re in April 2026, nearly four times the size, and the largest is a 1,056 MW development portfolio Exus Renewables acquired in December 2024. Ten of the 21 transactions in that period disclose no value at all, and most of the eleven that do are development-stage or portfolio deals, which is why the priced comparable set for an operating Polish wind asset is only four transactions wide. That is the practical limit on how precisely a Polish wind farm can be marked to market.
What does the deal signal for Polish wind?
It signals that the buyer pool for small operating Polish assets extends beyond the domestic utilities that dominate the record. Enea, PGE, Tauron, Orlen and Energa account for a large share of Polish wind transactions since 2024, and they buy at portfolio scale. A three-turbine farm is too small for them and for most infrastructure funds. It suits a listed company building a first operating position, and it prices accordingly.
It also marks a step in a strategy already visible in Enerdatics' record. In March 2026 Airengy bought six Polish solar companies totalling around 34 MW, structured so that each project transferred only after it reached commercial operation. That deal carried 15-year contracts for difference over roughly 62 percent of output. This one carries none, so buying it widens the exposure rather than repeating the trade. The contrast is instructive. Revolve Renewable Power recently agreed $1.09 million per MW for a wind farm in Montana, and the price there rested on a twenty-year power purchase agreement rather than on the turbines. Two operating wind farms, two very different per-megawatt outcomes, and the difference is the offtake.
Frequently asked questions
How much is Airengy paying for the FLUX wind project?Approximately EUR 13.5 million, equivalent to $15.71 million, for the 7.84 MW project, or $2.00 million per MW. The agreement is an agreement of principles rather than a binding purchase agreement, with completion expected by 31 December 2026.
What does it mean that the project sells on the free market?Its electricity is sold at prevailing Polish wholesale prices rather than under a contract for difference or a long-term power purchase agreement. The owner captures whatever the market pays, which raises both the upside and the volatility of the revenue the price is based on.
How does this price compare with other Polish wind deals?It sits mid-range. Among priced operating asset deals since the start of 2024, PPC Group paid $1.04 million per MW for 277 MW from EDP Renewables in July 2026, while Enea paid $2.43 million and $2.75 million per MW in two 2025 acquisitions.
Ready to get deal-ready answers in seconds? Try Enerdatics Leap AI and access verified intelligence across M&A, financings, PPAs, projects, and energy market developments through natural language.