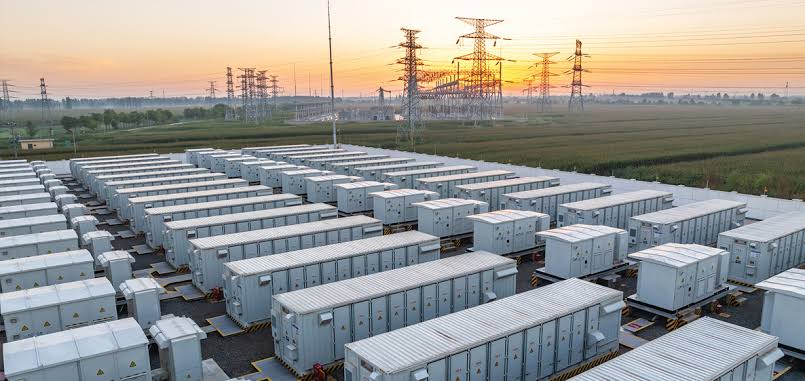
Why a 2.7 GW US Portfolio Deal Pays Out One Project at a Time
HASI has taken a minority stake in 2.7 GW of Invenergy solar, wind and battery projects spread across seven US states. Terms were not disclosed. The portfolio is large and the two companies have worked together for years, so the headline reads like a straightforward farm-down. The structure underneath it is not. Almost none of the money moves at closing.
Key takeaways
- HASI has acquired a minority stake in a portfolio of 10 utility-scale solar, solar plus storage and wind projects owned by Invenergy, totalling 2.7 GW across seven US states and six power markets. Terms were not disclosed.
- HASI is funding the investment project by project, providing capital for each project as it reaches commercial operations rather than funding the whole portfolio at closing.
- More than 850 MW of the 2.7 GW portfolio is operational today, with the remaining projects expected to begin operations by the first quarter of 2027.
- Invenergy started the process in March 2026, appointing CIBC Capital Markets to market a stake of up to 49 percent, and retains control, majority ownership and day-to-day operation of the projects.
- Enerdatics records 25 US minority-stake renewable energy transactions since the start of 2024, of which only 10 carry a disclosed value. The five priced asset-level solar and wind deals among them imply $1.02 million to $2.40 million per MW once the consideration is grossed up to 100 percent of the asset.
What is HASI actually buying today?
Less than a third of what the headline capacity suggests. Enerdatics records more than 850 MW of the 2.7 GW as operational, with the rest due to come online by the first quarter of 2027. On the funding terms described, capital is provided for each project as that project reaches commercial operations. The projects that are already running can be funded now. The others cannot.
That turns a single announced transaction into a sequence of smaller ones stretched over roughly the next eighteen months. The 2.7 GW figure describes the size of the commitment, not the size of the payment. It is the difference between agreeing to buy a building and agreeing to buy each floor as it is finished.
Enerdatics understands the portfolio to include the 450 MW Chalk Bluff solar project in Arkansas and the 340 MW Alle-Catt wind project in New York, both under construction with commercial operation expected in the first quarter of 2027, the 275 MW Hashknife I solar project in Arizona with 275 MW of co-located storage, the 240 MW Cadence solar project in Ohio which reached operations in January 2026, the 200 MW Trade Post solar project in Indiana, and the 103.9 MW Number Three wind project in New York, operating since May 2023. Enerdatics describes this project list as its own understanding rather than a disclosed schedule.
Why does funding at commercial operations change the risk?
Because it leaves construction risk where it started. A farm-down is the sale of a minority position in assets the seller has developed, used to recycle capital into the next round of projects while keeping control of the current ones. In most farm-downs the buyer pays at completion and then carries a share of whatever happens next, including cost overruns and delays on anything still being built.
Here the payment is attached to the event that ends construction risk rather than to the signing of the agreement. If a project slips, the capital for it waits. If a project does not reach operations at all, the capital for it is never called. Invenergy absorbs the delay and HASI absorbs the timing.
This is a familiar shape in deals for assets that are not finished. An Alberta solar and battery purchase Enerdatics covered in August placed 98.6 percent of its headline price behind future milestones, with only cash at closing payable up front. The mechanism here is gentler, because more than 850 MW is already generating, but the logic is the same one.
What does Invenergy get that an outright sale would not give it?
Cash without loss of control. Invenergy keeps majority ownership and continues to run the projects, so the operating platform and the customer relationships stay in one place. What leaves is a share of the equity, and with it the capital tied up in assets that are finished or nearly finished.
For a developer with a continuous pipeline, that capital is worth more deployed into the next set of projects than parked in completed ones. The pattern is not confined to the US: when KKR bought into RWE's Norfolk Vanguard offshore wind projects, the same division of labour applied, with the developer originating and de-risking and infrastructure capital arriving to carry the balance sheet.
HASI has structured repeat exposure to a single counterparty before. Its joint venture with Ameresco in the advanced biofuels business committed $400 million against a defined growth programme rather than a one-off purchase. Buying into a partner's pipeline in instalments is closer to how this investor works than a single dated acquisition would be.
Enerdatics records 25 US minority-stake renewable energy transactions since the start of 2024, of which only 10 carry a disclosed value. Among the five priced asset-level solar and wind deals, grossing the consideration up to 100 percent of the asset gives a range from $1.02 million per MW, on Stonepeak's April 2025 purchase of 46.3 percent of a 777 MW Repsol portfolio, to $2.40 million per MW on MDU Resources' February 2025 purchase of 49 percent of the 250 MW Badger wind farm from Orsted. Ares Management's 49 percent of a 1.6 GW EDP Renewables portfolio in October 2025 sits at $1.78 million per MW on the same basis. This deal adds no price to that set.
What does the deal signal for the US renewables market?
That the farm-down is becoming a financing instrument rather than an exit. Nothing about this transaction resembles a developer stepping back. Invenergy keeps the majority, keeps operations and keeps the customer contracts, and sells a slice of equity on terms that pay out as the assets complete.
The offtake profile explains why a buyer will accept that. The projects are backed by long-term agreements with investment-grade counterparties, including a 100 MW virtual power purchase agreement with Verizon and a separate agreement with Meta covering the remaining 350 MW at Chalk Bluff, a long-term contract with Arizona Public Service covering the Hashknife I solar output and its four-hour battery, and 20-year index renewable energy certificate contracts with NYSERDA for the two New York wind farms. Revenue certainty at that level is what makes staged funding acceptable, because the cash flow each tranche buys is known before the tranche is paid.
The price stays hidden, as it usually does. Ten disclosed values out of 25 minority-stake transactions since the start of 2024 is the market norm, not an omission, and it means the pricing signal in US farm-downs has to be assembled from a small number of deals rather than read off the tape.
Frequently asked questions
What did HASI buy from Invenergy?A minority stake in a 2.7 GW portfolio of 10 utility-scale solar, solar plus storage and wind projects across seven US states and six power markets. Invenergy retains control and majority ownership. Terms were not disclosed.
How much of the portfolio is already operating?More than 850 MW, with the remaining projects expected to reach commercial operations by the first quarter of 2027.
Who advised on the transaction?CIBC Capital Markets acted as financial adviser and Sidley Austin as legal adviser to Invenergy. Baker McKenzie acted as legal adviser to HASI.
Track US renewable energy M&A, financings and PPAs as they are recorded. Explore the Enerdatics Insights page.