Why a Valencia Battery Portfolio Is Sized for Five Hours When Spain Builds Four
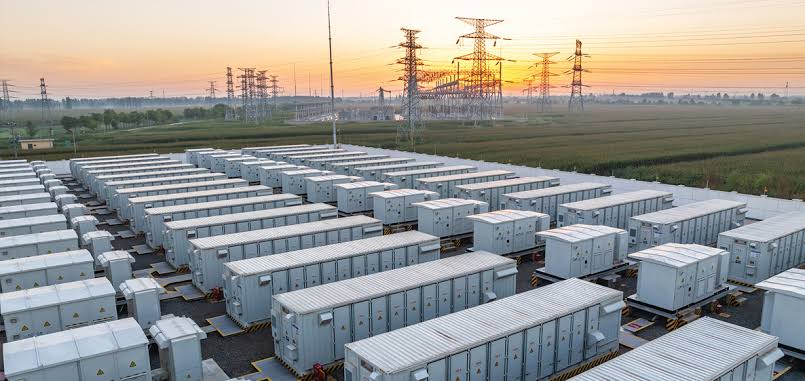
BW ESS has bought two battery projects in the Valencia region of Spain from Navacant Energy. Enerdatics records the portfolio at 126 MW of power capacity and up to 675 MWh of energy capacity. Terms were not disclosed. Divide the second number by the first and the answer does not match anything else Spain has traded.
Key takeaways
- BW ESS, the energy storage business of BW Group, has acquired the Project Sorolla battery portfolio in Spain from Navacant Energy. Terms were not disclosed.
- The portfolio comprises two utility-scale standalone battery projects in the Valencia region, one of 99 MW and one of 27 MW, each with symmetric grid connection capacity, and Enerdatics records it at 126 MW and up to 675 MWh.
- Up to 675 MWh on 126 MW describes a system able to run for roughly 5.4 hours at full output, against a Spanish market where the recorded battery deals cluster at four hours.
- The projects have been under development for around 18 months, are expected to reach ready-to-build status in 2027 and are targeted for commercial operations in 2028.
- CST Energy, a partner of Navacant Energy, will continue to lead the projects through the remaining development phase until ready-to-build, after which BW ESS will lead construction and delivery into operation.
How long can Project Sorolla actually run?
Energy capacity divided by power capacity gives duration, the length of time a battery can sustain its full rated output before it is empty. A 100 MW system with 400 MWh behind it runs for four hours. The same 100 MW with 200 MWh runs for two.
Applying that to the recorded figures puts Project Sorolla at roughly 5.4 hours. That is the arithmetic on 126 MW and 675 MWh, and it is the single most useful thing the announcement discloses, because duration decides what a battery is commercially for. Short systems earn from frequency response and the sharp evening peak. Longer systems can move midday solar output into the evening and hold position through a wider spread.
The energy figure carries a qualification worth keeping. It is stated as up to 675 MWh, not as a fixed specification, on projects that will not be built for another two years. Treat 5.4 hours as the upper bound of the design rather than the number that will appear on the commissioning certificate.
Why is five hours unusual in the Spanish market?
Because nothing else in the record set reaches it. Enerdatics records 12 Spanish battery storage transactions since the start of 2024. Five of those state both power and energy capacity, and four of the five sit at or just below four hours: a 66 MW and 264 MWh project ENGIE bought from Arena Power, an 80 MW and 318 MWh portfolio Return Storage bought from Aquila Capital, a 32 MW and 128 MWh portfolio in which Endurance Motive took a 30 percent stake, and a 278 MW portfolio with 1.1 GWh that ENGIE bought from Rolwind Group. Project Sorolla is the only one above four hours.
Four hours is not an accident of engineering. It is the point at which a Spanish battery can cover the evening ramp as solar output falls away, and it is where developers have been sizing projects to keep capital cost proportionate to the revenue on offer. Going past it means paying for cells that only earn in the wider price spreads, which is a view about future volatility rather than a view about today's.
It is also consistent with how this buyer has been shopping. The 1 GW German project BW ESS took full ownership of earlier in 2026 is configured at up to 5.7 GWh, another system built well beyond the two-hour and four-hour conventions. Two long-duration acquisitions in two markets within three months looks like a preference rather than a coincidence.
Duration is also where recorded capacity and permitted capacity can part company. The battery ENGIE bought in Andalusia is recorded at four hours but holds an authorisation describing a smaller energy capacity. On an early-stage Spanish project, the megawatt-hour figure is a design intention until the permit says otherwise.
Who finishes the development work, and why does it matter?
Not the buyer, for about another year. CST Energy, a Navacant Energy partner, continues to lead the projects to ready-to-build status, the point at which permits, grid rights and contracts are complete and construction can start. Only then does BW ESS take the wheel for construction and delivery.
That split is the commercial substance of the transaction. Development risk between now and 2027 stays with the party that has been carrying it for the past eighteen months and knows the sites, the local authorities and the grid position. The buyer takes the risk it is equipped for, which is building and operating, and pays for a project it expects to receive in a defined condition.
The alternative arrangement is visible elsewhere. In Finland, Byhmgard bought a 50 MW battery project and took on the remaining development work itself, with payment staged against reaching ready-to-build. Both structures answer the same question about who is best placed to finish a half-developed asset. They answer it differently.
Enerdatics records 12 Spanish battery storage transactions since the start of 2024, of which only three carry a disclosed value, and not one of the three supports a price per megawatt: two are minority or platform stakes and the third records no power capacity. Spanish storage is being traded at a rate of roughly one deal a month with almost no visible pricing, which makes structural detail of this kind the main thing a comparable transaction can actually tell a buyer.
What does the deal signal for the Spanish storage market?
That the competition is moving to early-stage projects with a long design. Project Sorolla is roughly eighteen months into development and two years from ready-to-build, and it has attracted an international owner-operator, a financial adviser in JLL Capital Markets, and technical and legal diligence from Mott MacDonald and Watson Farley and Williams. That is an institutional process for an asset that does not yet have a construction start date.
The duration choice points at where the returns are expected to come from. A four-hour fleet is sized for the evening ramp. A portfolio designed past five hours is sized for a market with wider and less predictable spreads, driven by rising solar penetration and the curtailment that comes with it. Buyers making that bet are underwriting volatility several years out, on assets that will not earn anything until 2028.
What the market still does not produce is a price. Three disclosed values across twelve transactions, none of them usable as a benchmark per megawatt, means Spanish storage valuations continue to be inferred from structure, stage and duration rather than read from the record.
Frequently asked questions
What is Project Sorolla?A portfolio of two utility-scale standalone battery energy storage projects in the Valencia region of Spain, one of 99 MW and one of 27 MW, with a combined 126 MW of power capacity and up to 675 MWh of energy capacity. Ready-to-build status is expected in 2027 and commercial operations in 2028.
What does battery duration mean?Duration is energy capacity divided by power capacity, the number of hours a battery can run at full output before it is empty. It determines which markets the asset can earn in.
Who advised on the transaction?JLL Capital Markets acted as financial adviser to Navacant Energy. Watson Farley and Williams acted as legal adviser and Mott MacDonald as technical adviser to BW ESS.
Track European battery storage M&A, financings and PPAs as they are recorded. Explore the Enerdatics Insights page.