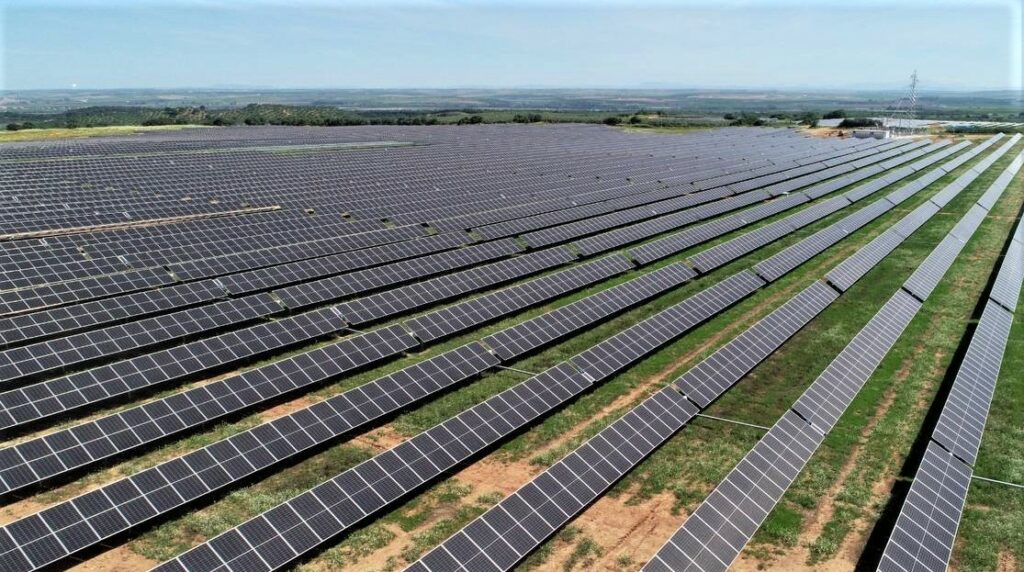
Intermediate Capital Group is buying more than 500 MW of Spanish solar that has not been built. Three projects, in Castilla y Leon and Andalusia, at the earliest stage Enerdatics tracks. No price was disclosed, which is normal for a deal of this kind, and that is the difficulty. Spain has produced only three early-stage solar transactions since the start of 2024, and not one of them says what early-stage Spanish solar is worth.
Key takeaways
- Intermediate Capital Group's Dos Grados has agreed to acquire three under-development solar projects in Spain with a combined capacity of more than 500 MW from Akuo Energy, owned by Ardian Infrastructure. The consideration was not disclosed.
- The projects sit in Castilla y Leon and Andalusia and are classified by Enerdatics as early-stage, the stage at which a project has been announced or is in environmental assessment but has not yet been approved.
- Enerdatics records three early-stage Spanish solar transactions since the start of 2024, including this one, and none of the three carries a disclosed value.
- Operational Spanish solar has traded at a median implied enterprise value of $0.90 million per MW across 14 priced deals since the start of 2024. The median developer premium on Spanish development-stage solar is $0.10 million per MW, drawn from four priced deals, a sample Enerdatics flags as below its own minimum for a firm benchmark.
- Spanish solar dealmaking has thinned sharply: Enerdatics records 28 transactions in 2024, 28 in 2025 and eight so far in 2026.
What does early-stage mean in a Spanish solar deal?
It means almost nothing has been settled. Enerdatics classes a project as early-stage when it has been announced or is working through environmental assessment, which sits well before the ready-to-build stage where a project has its approvals, its grid connection and a notice to proceed. At early stage there is no construction contract, no commissioning date and no offtake. What changes hands is a land position, a grid application and whatever progress has been made through planning.
That stage is also rare in the traded Spanish market. Of the 24 Spanish solar deals involving assets under development since the start of 2024, Enerdatics records 11 at ready-to-build, seven at late stage and three at early stage. Buyers have been concentrating at the end of the development pipeline where the risk has already been removed, which is what makes a 500 MW early-stage purchase worth a second look.
What is Dos Grados actually buying for its money?
Land access with an agricultural use attached. The portfolio is agrivoltaic, meaning the panels are arranged so the ground underneath stays in agricultural or other economic use rather than being given over to generation alone. Intermediate Capital Group has said it intends to promote that coexistence model and to draw on Akuo Energy's experience in fitting renewable plants around local land uses, alongside integrating energy management technology and serving industrial energy demand.
In Spain that is a sharper proposition than it sounds. Sunlight is not the constraint. Grid access and local consent are, and a project designed to leave farmland farming is easier to consent than one that does not. The revenue side is harder. Spanish solar has been earning less for what it generates as midday output has grown, which is why operating portfolios have been changing hands at compressed capture prices and why the stated plan to serve industrial demand matters more than the agricultural framing.
Why does nobody disclose a price for a project like this?
Because there is rarely a single price to disclose. Consideration for development-stage assets is usually staged against milestones such as environmental approval, grid connection and notice to proceed, so one headline figure would misdescribe the deal rather than explain it. The structure also protects the buyer, who is paying for an outcome that has not happened yet.
The gap that opacity hides is wide. Enerdatics puts the median developer premium, the amount paid per MW for development-stage pipeline, at $0.10 million per MW for Spanish solar since the start of 2024, within a range of $0.06 million to $0.13 million. At that median, more than 500 MW would be worth on the order of $50 million. The figure rests on four priced deals, which is below the five Enerdatics requires before it treats a benchmark as firm, so it is an order of magnitude rather than a valuation. Ready-to-build Spanish solar, by contrast, has priced at a median implied enterprise value of $0.79 million per MW across four priced deals, and operational Spanish solar at $0.90 million per MW across 14.
Enerdatics records 64 Spanish solar transactions since the start of 2024, carrying $5.81 billion of disclosed value between them, and the distribution tells the story of where capital has been going. The 25 operational deals include 14 with a price, at a median of $0.90 million per MW and a range running from $0.69 million to $5.00 million. The 12 in-construction deals include three with a price, at a median of $0.78 million per MW. The 24 development-stage deals include eight with a price, at a median implied enterprise value of $0.60 million per MW. Deal count, meanwhile, has fallen from 28 in each of 2024 and 2025 to eight so far in 2026.
What does the deal signal for the Spanish solar market?
It signals a bet against the direction the rest of the market has taken. Spanish renewables dealmaking has moved towards operating asset farm-downs, in which owners sell minority stakes in commissioned portfolios to recycle capital, and towards older regulated plants bought for their remaining revenue life. Both are purchases of certainty. Three unapproved projects are the opposite trade.
The reading that makes it coherent is that the scarce asset in Spain is no longer a solar plant but permission to build one in a place where the grid can take the power and the community will accept the land use. If that is right, a credit-led manager buying at the front of the pipeline is buying the bottleneck rather than the megawatts, and the agrivoltaic design is a permitting strategy as much as an agricultural one. The test arrives when these projects reach ready-to-build, the one stage where the Spanish market does print a price.
Frequently asked questions
How much did Intermediate Capital Group pay for the Spanish solar portfolio?The consideration was not disclosed. Enerdatics records three early-stage Spanish solar transactions since the start of 2024, including this one, and none carries a disclosed value.
What is agrivoltaics?Agrivoltaics is solar generation designed so the land beneath and around the panels stays in agricultural or other economic use, instead of being converted to energy production alone. It is used in Spain and Italy partly because it eases the permitting and local consent that constrain new solar build.
What is a developer premium?A developer premium is the amount a buyer pays per MW for development-stage pipeline, as distinct from the enterprise value per MW paid for an operating plant. Enerdatics puts the median for Spanish solar since the start of 2024 at $0.10 million per MW, from a sample of four priced deals.
Ready to get deal-ready answers in seconds? Try Enerdatics Leap AI and access verified intelligence across M&A, financings, PPAs, projects, and energy market developments through natural language.