Why Two Projects Carry the Economics of a 2.3 GW Battery Deal
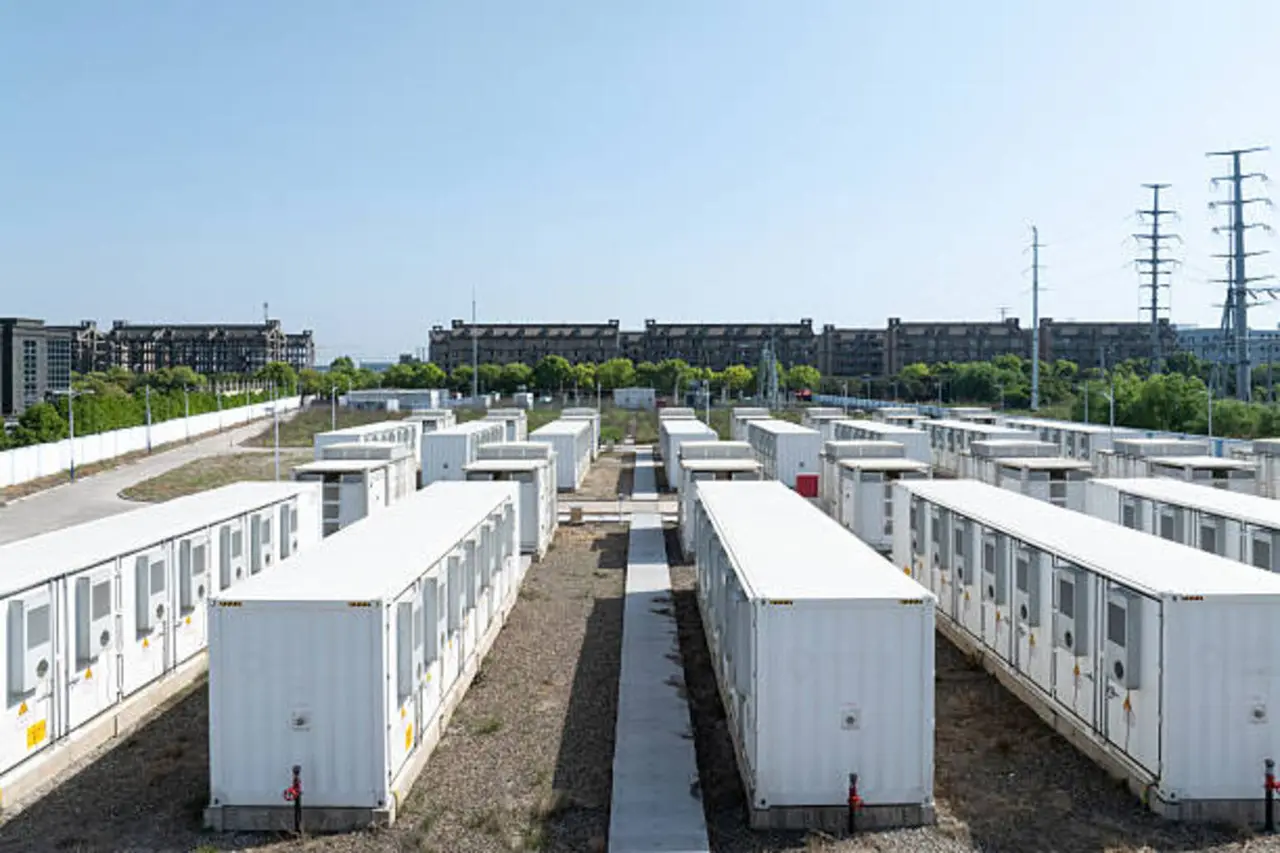
Energy Vault has bought a platform holding 2.3 GW of US battery projects. Two of them are ready to build. The other thirteen are not, and the company expects the platform to reach more than $200 million of run-rate earnings by 2028. The gap between those two facts is the whole transaction.
Key takeaways
- Energy Vault has acquired 100 percent of the membership interests in Development Vault, LLC, a platform holding approximately 2.3 GW of US battery storage development projects, from Goshe Energy Storage. The consideration was not disclosed.
- The acquired portfolio comprises about 2.3 GW across 15 projects, of which 350 MW is ready to build, made up of one 150 MW project and one 200 MW project, both expected to reach commercial operation in the first quarter of 2028.
- The two ready-to-build projects are expected to generate approximately $30 million of combined annual run-rate EBITDA once operational, against a platform target of more than $200 million of run-rate EBITDA on exit in 2028.
- Development Vault had secured a credit facility commitment of up to $40 million from S2G Investments, and Goshe Energy Storage's leadership team and development staff are joining Energy Vault.
- Of the six US development-stage battery asset acquisitions with a disclosed value recorded by Enerdatics since the start of 2024, five were in ERCOT and priced between roughly $29,000 and $74,000 per MW, with the sixth, in CAISO, at $400,000 per MW.
What did Energy Vault actually buy?
It bought a holding company assembled for the purpose. Goshe Energy Storage contributed certain direct and indirect subsidiaries into Development Vault, LLC before closing, and Energy Vault then acquired 100 percent of the membership interests in that entity. A membership interest purchase agreement transfers ownership of a limited liability company itself rather than the assets inside it, so the projects, their contracts and their permits move across without being individually reassigned.
That structure matters more for a development portfolio than for an operating one. A battery project under development is mostly a bundle of paper: land rights, an interconnection position in the grid operator's queue, environmental clearances and equipment orders. Reassigning those one by one risks losing a queue position or triggering a counterparty consent. Buying the company that holds them avoids the question. The people came too, with Goshe's leadership team and development professionals joining Energy Vault, which for a development business is much of what is being bought.
Why does 350 MW matter more here than 2.3 GW?
Because ready to build is the point at which a project stops being a probability. A ready-to-build battery has site control, an executed interconnection agreement and its permits in hand, so what remains is construction and market risk rather than development risk. Two of the 15 projects meet that test, at 150 MW and 200 MW, both scheduled to reach commercial operation in the first quarter of 2028. That is a little over 15 percent of the 2.3 GW headline.
Enerdatics has identified the 150 MW and 339 MWh Two Brothers project in Victoria County, Texas as one of the two ready-to-build projects, based on project-level references contained in Development Vault's financing documentation. That identification is Enerdatics' own reading of the documents rather than a confirmed disclosure. Taking the figures as given, Two Brothers holds 339 MWh behind 150 MW of power, a duration of about 2.3 hours. Duration is energy capacity divided by power rating, and it sets what a battery can sell. A two-hour battery captures the daily spread between cheap afternoons and expensive evenings. It cannot serve a long system shortage.
What does ready-to-build battery capacity cost in Texas?
Less than most readers would guess, because the buyer still has to build it. Enerdatics records 42 US battery storage acquisitions involving development-stage assets since the start of 2024, and seven of them carry a disclosed value. Six of those seven are asset transactions. Nofar Energy paid Ormat Technologies $40 million for a 100 MW and 400 MWh project in CAISO in July 2026, which is $400,000 per MW and stands alone at the top of the range. The other five all sat in ERCOT and all sat far below it. Cerberus Capital Management and Eos Energy paid Bimergen Energy $8.9 million for 120 MW in May 2026, about $74,000 per MW, the top of that group. Gridstor paid Balanced Rock Power $15 million for the 220 MW Hidden Lakes project in March 2024, about $68,000 per MW. At the bottom, Nofar paid Qcells $10 million for 350 MW in March 2025, about $29,000 per MW.
Set that against the earnings. Priced on the ERCOT range, 350 MW of ready-to-build capacity would change hands for somewhere between $10 million and $26 million. The same 350 MW is expected to produce approximately $30 million of combined annual run-rate EBITDA once operational. The purchase price of a development-stage battery is therefore a fraction of a single year of the earnings it will eventually throw off, because the construction capital sits entirely outside that number. Neither the consideration for Development Vault nor the cost of building the portfolio has been disclosed.
Enerdatics records five Energy Vault acquisitions since the start of 2024: the 150 MW SOSA project in Texas, the 175 MW McMurtre project in ERCOT North, a 125 MW project in Australia, an 850 MW portfolio in Japan and now Development Vault. Not one carries a disclosed value in Enerdatics' structured deal value field, which makes this buyer one of the more opaque acquirers in storage despite being publicly listed.
What does the deal signal for US battery storage?
It signals that a technology vendor has finished becoming an asset owner. Energy Vault has spent two years buying projects to run itself, first the 150 MW SOSA project in Texas under its Asset Vault platform, then a 175 MW project in ERCOT North with interconnection and site control already executed. Buying single de-risked assets gets you megawatts. Buying a development company gets you the capacity to originate them.
The 2028 earnings target is what makes the other thirteen projects load-bearing. Two ready-to-build projects deliver roughly $30 million of run-rate EBITDA. The stated ambition is more than $200 million. The remaining $170 million has to come from projects holding neither a completed interconnection agreement nor a construction schedule, on a portfolio backed by a credit facility commitment of up to $40 million. That is a development plan rather than a forecast, and it is the same bet on pipeline scale Energy Vault made when it acquired an 850 MW storage pipeline in Japan.
Frequently asked questions
How much did Energy Vault pay for Development Vault?The consideration was not disclosed, which is normal here. Enerdatics records 42 US development-stage battery storage acquisitions since the start of 2024, and only seven carry a disclosed value. None of Energy Vault's own five carries one in Enerdatics' structured record.
What does ready to build mean for a battery project?A ready-to-build project has completed the development work needed to start construction, which typically means site control, an executed interconnection agreement with the grid operator and the required permits. The remaining risks are building the project on time and on budget, and earning the revenue once it operates, rather than whether it can be built at all.
How much of the 2.3 GW portfolio can be built now?Approximately 350 MW, spread across one 150 MW project and one 200 MW project, both targeting commercial operation in the first quarter of 2028. The remaining 13 projects in the 15-project portfolio are at earlier stages of development and no construction timetable for them has been disclosed.
Ready to get deal-ready answers in seconds? Try Enerdatics Leap AI and access verified intelligence across M&A, financings, PPAs, projects, and energy market developments through natural language.