How Enbridge Bought Back the Hohe See Stake It Sold in 2018

In 2018 Enbridge sold a 24.45 percent stake in two German offshore wind farms, Hohe See and Albatros, to CPP Investments. Five years later it agreed to buy the same stake back. The price, once measured properly, is the highest per megawatt of any operating German offshore wind deal Enerdatics has recorded since 2021.
Key takeaways
- CPP Investments agreed on 3 November 2023 to sell its 24.45 percent stake in the Hohe See and Albatros offshore wind farms in Germany to a wholly owned subsidiary of Enbridge for a total consideration of $663.5 million.
- The $663.5 million Hohe See and Albatros consideration comprises $283.5 million in cash and $380 million of assumed debt, and CPP Investments expected net proceeds of about $271 million after costs and adjustments.
- Grossed up to a 100 percent basis, the Enbridge transaction values the 639.45 MW Hohe See and Albatros wind farms at about $2.71 billion, or about $4.24 million per MW.
- Hohe See and Albatros sell power under Germany's feed-in tariff regime for 20 years, at $207 per MWh for the first 8 years, $167.82 per MWh for the next 5 and a floor of $44 per MWh for the remaining 7, which Enerdatics calculates as a weighted average of $124 per MWh over the remaining contracted life.
- After the deal Enbridge owns 49.89 percent of Hohe See and Albatros and EnBW, which built the wind farms, retains 50.11 percent.
Why would Enbridge buy back a stake it sold?
Because the wind farms had moved from a risk worth sharing to an income worth owning. Enbridge acquired 49.9 percent of Hohe See and Albatros from EnBW in February 2017, when the projects were still to be built. In 2018 it sold half of that position, 24.45 percent of the projects, to CPP Investments. Selling down during construction is a common way for a developer to share capital needs and recover cash early.
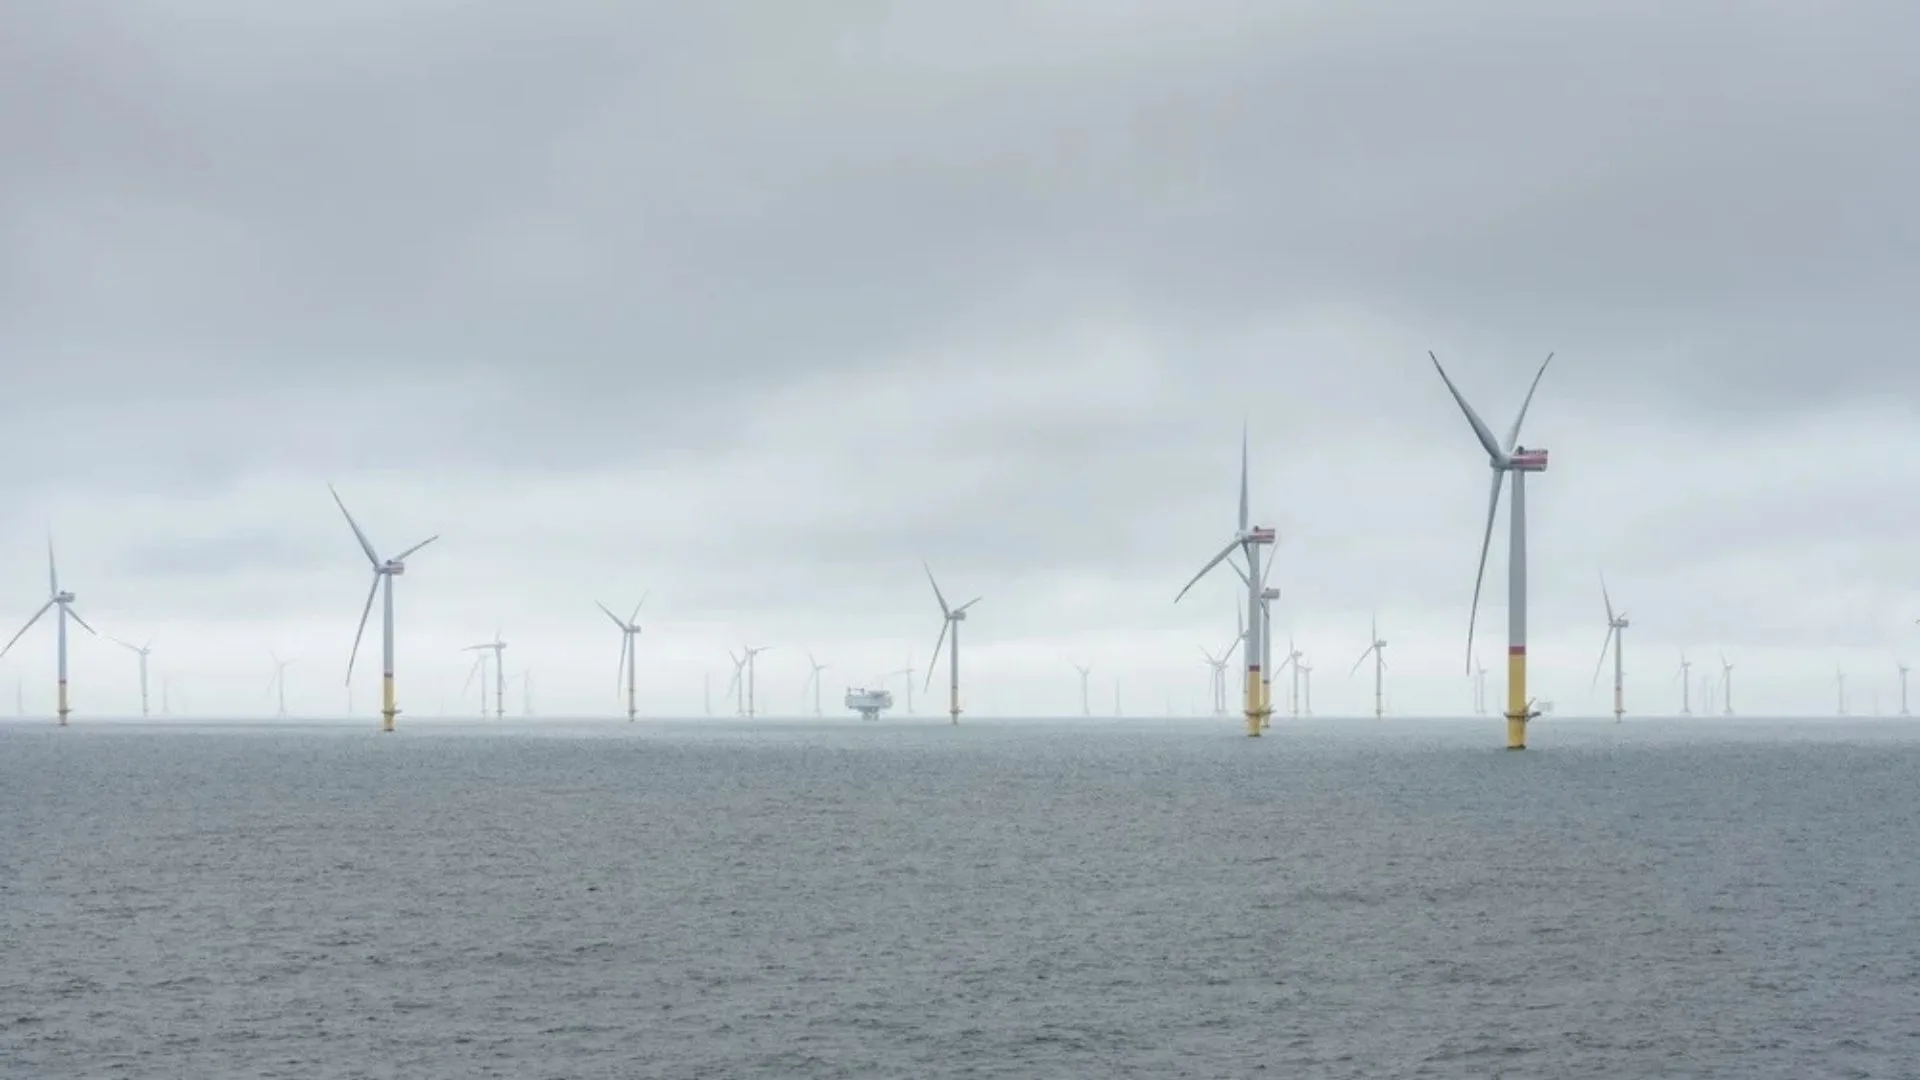
By 2023 the risk profile had changed. Hohe See was connected to the grid in October 2019 and Albatros in January 2020. EnBW built them as one 639.45 MW joint project about 100 km off the German North Sea coast, with 71 turbines of 7.35 MW at Hohe See and 16 at Albatros. Together they supply energy to more than 700,000 households.
An operating wind farm on a fixed tariff behaves much like a bond. Its output can be estimated and its price per MWh is set by law. For a company like Enbridge, buying more of an asset it already co-owns and knows well is a low-risk way to add stable earnings. For CPP Investments, the sale crystallised the value of a construction-stage investment.
How does $663.5 million become $4.24 million per MW?
By correcting for the size of the stake. The headline consideration buys 24.45 percent of the wind farms, not all of them. Divide $663.5 million by the full 639.45 MW and the result is about $1.04 million per MW, the figure a structured database field shows. That compares a minority price with full capacity and understates the valuation about fourfold.
Grossing up fixes the comparison. Dividing $663.5 million by 24.45 percent gives a value of about $2.71 billion for the whole of Hohe See and Albatros. Spread over 639.45 MW, that is about $4.24 million per MW.
The consideration also mixes cash with debt. Of the $663.5 million, $283.5 million is cash and $380 million is debt that Enbridge assumes. That debt traces back to 2020, when CPP Investments raised $557 million by issuing German law registered notes to select investors. Under the deal, the outstanding principal on those notes passes to an Enbridge-owned entity. Counting the cash alone, the equity values the whole project at about $1.81 million per MW. The higher figure is the one used for comparison below, because it captures the full value of what changed hands, debt included.
What does the feed-in tariff contribute to the price?
Most of it. A feed-in tariff is a fixed price per MWh guaranteed by the state for a set period. Hohe See and Albatros receive $207 per MWh for their first 8 years, then $167.82 per MWh for 5 years, then a floor of $44 per MWh for the final 7. Enerdatics calculates the weighted average over the remaining contracted life at $124 per MWh.
The deal was struck early in that schedule. The wind farms were about four years into the first, highest tariff period, so the buyer was paying for several more years at $207 per MWh followed by five years at $167.82. Those are high prices by the standards of new offshore wind. Enerdatics' analysis of Glennmont's purchase of half of Gode Wind 3 shows the same pattern: subsidy vintage can matter as much as build stage.
The tariff also explains why the value falls over time. Once the higher periods end, the floor of $44 per MWh offers far less support. An owner buying in 2023 captures the richest years. An owner buying in 2030 would not.
Enerdatics records 15 German offshore wind M&A transactions with a disclosed value announced between 2021 and 2024. Grossed up to a 100 percent basis, the operating asset deals range from about $2.15 million per MW for Equitix's 15.2 percent of Gode Wind 1 in August 2024 to $4.24 million per MW for Enbridge's purchase of Hohe See and Albatros. Energy Infrastructure Partners' 49 percent of Iberdrola's 350 MW Wikinger in 2022 grosses up to about $4.11 million per MW, and Greencoat Renewables' 22.5 percent of the 288 MW Butendiek in January 2023 to about $4.09 million per MW. Two later Butendiek stake sales in October and November 2023 priced at about $3.60 million per MW. Hohe See and Albatros sit at the top of the operating range.
What does the deal signal for German offshore wind?
It signals that tariff-backed operating offshore wind remains the most highly priced asset in the German market. The buyer was an existing owner, the asset was fully built, and the revenue was set by law for years ahead. Those three conditions together produced the top price on Enerdatics' recent record.
It also shows that construction-stage partners and long-term owners are not always the same investors. CPP Investments came in during construction and left once the wind farms were running. Enbridge sold during construction and bought back once they were running. EnBW kept its majority throughout. A similar pattern of utilities selling into construction and investors pricing by stage runs through Enerdatics' analysis of the valuation behind Masdar's Baltic Eagle stake.
Frequently asked questions
How much did Enbridge pay for CPP Investments' stake in Hohe See and Albatros? Enbridge agreed to a total consideration of $663.5 million for the 24.45 percent stake, made up of $283.5 million in cash and $380 million of assumed debt. Grossed up to 100 percent, that values the wind farms at about $4.24 million per MW.
Who owns Hohe See and Albatros after the deal? After the transaction Enbridge owns 49.89 percent and EnBW retains 50.11 percent. CPP Investments exits the assets entirely.
Who advised on the Hohe See and Albatros sale? RBC Capital Markets acted as exclusive financial adviser to CPP Investments and Clifford Chance as its legal adviser. Dentons acted as legal adviser to Enbridge.
Ready to get deal-ready answers in seconds? Try Enerdatics Leap AI and access verified intelligence across M&A, financings, PPAs, projects, and energy market developments through natural language.