EDP has sold 80 percent of three newly built US solar parks to Eni's Plenitude in a transaction carrying a $400 million enterprise value. The portfolio totals 339.9 MW. Divide one number by the other and the deal looks slightly below the going rate for operating US solar. Adjust for the stake and it looks well above it. The difference is a single question about what the $400 million covers.
Key takeaways
- EDP announced on 4 January 2024 an agreement to sell an 80 percent equity stake in a 339.9 MW portfolio of three operating US solar projects to Eni's Plenitude, through Eni New Energy US, at an enterprise value of $400 million; the sale completed on 15 February 2024.
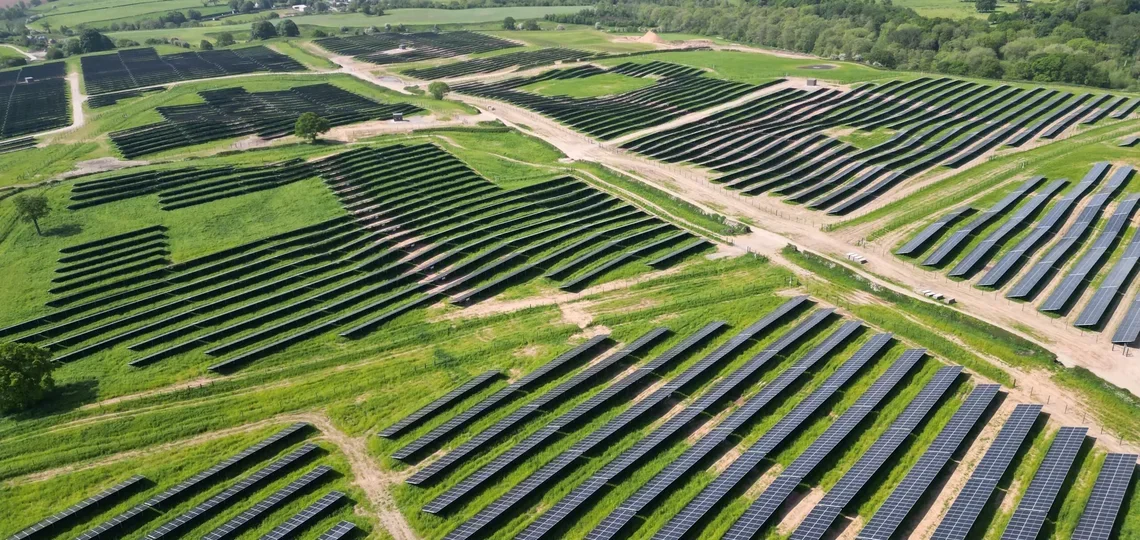
- The EDP portfolio sold to Plenitude comprises the 240 MW Cattlemen solar park in Milam County, Texas, the 50 MW Timber Road solar park in Paulding County, Ohio, and the 49.9 MW Blue Harvest solar park in Putnam County, Ohio.
- Cattlemen sells power to Meta (156 MW) and Bristol Myers Squibb (60 MW for 15 years), Blue Harvest has a PPA with Amazon, and Timber Road sells its entire output into the PJM wholesale market, according to FERC data.
- Leap prices the EDP to Plenitude transaction at $1.47 million per MW when the $400 million is treated as the value of the 80 percent stake and grossed up to 100 percent, against $1.18 million per MW on the unadjusted figure.
- Enerdatics records a median of $1.25 million per MW across 17 priced operational US solar asset deals announced in 2023 and 2024, which places the grossed-up EDP figure about 18 percent above the median.
Why does the price per MW have two answers?
Because the stake and the capacity do not match. Plenitude bought 80 percent of the portfolio, while the 339.9 MW figure describes all of it. Dividing a consideration for part of an asset by the capacity of the whole understates the price.
EDP described the $400 million as an enterprise value. Enterprise value normally means the value of the whole business including its debt, which would make the unadjusted $1.18 million per MW the right reading. Leap's benchmarking engine instead treats the $400 million as the price of the 80 percent and grosses it up to $500 million for 100 percent, which is where $1.47 million per MW comes from. The original version of this post used that higher figure, and it is the one Leap reports.
Neither reading changes the facts of the sale. It changes where the deal sits in the market. At $1.18 million the portfolio traded slightly below the US median. At $1.47 million it traded in the top quarter.
What makes these three parks worth a premium?
Mostly their age and their buyers. Leap's record notes that, according to November 2023 EIA data, all three projects were expected to begin operating in December 2023. Enerdatics estimates the asset maturity at the time of the deal at about one month. Plenitude bought assets with almost their entire working life still ahead of them.
The contracts matter as much. Cattlemen, the largest of the three, has 216 MW of its 240 MW committed to two corporate buyers, Meta and Bristol Myers Squibb. Blue Harvest supplies Amazon's offices, fulfilment centres and Amazon Web Services data centres. Corporate power purchase agreements with technology and pharmaceutical buyers of that standing are among the most sought-after revenue streams in US renewables.
Only Timber Road is uncontracted. Its 50 MW, about 15 percent of the portfolio, sells into PJM, the wholesale market covering much of the US mid-Atlantic and Midwest. That merchant slice adds price risk, but it is small relative to the contracted base.
Why is EDP selling assets it has only just built?
Because selling stakes in newly completed projects is the core of its funding model. EDP made the sale through EDP Renewables, its 71.27 percent owned subsidiary, as part of an asset rotation programme for 2023 to 2026. Asset rotation means building projects, selling a large share once they are operating, and reinvesting the proceeds in new development.
EDP said that with this transaction it had executed and secured more than 25 percent of the roughly $7.6 billion programme. Selling 80 percent rather than 100 percent recovers most of the capital while leaving EDP with a 20 percent stake in the portfolio. EDP has also run the strategy in reverse when the timing suits it, as in its buyback of 49 percent of a 970 MW European wind portfolio from China Three Gorges.
Marathon Capital acted as financial adviser to EDP Renewables.
Enerdatics' data shows where the deal sits among its peers. Enerdatics records 39 operational US solar asset transactions announced in 2023 and 2024, of which 17 carry a value that converts to a price per MW. Their median is $1.25 million per MW, the interquartile range runs from $1.01 million to $1.34 million, and the full range from $0.24 million to $2.12 million. Nearby prints include a 180 MW deal at $240 million, or $1.33 million per MW, in March 2024, a 100 MW deal at an estimated $1.25 million per MW in January 2024, and a 282 MW deal at an estimated $1.21 million per MW in October 2023. The bottom of the range is HASI's $143 million structured investment in a 605 MW AES portfolio, announced on the same day as the EDP sale.
What does the deal signal for US operating solar?
It signals that brand-new, corporate-contracted solar commands the top of the US price range. A portfolio with a month of operating history and three household-name offtakers carries less risk than an older fleet with utility contracts nearing expiry, and buyers price that in.
It also signals how much care US solar benchmarks need. The gap between $1.18 million and $1.47 million per MW is the difference between a below-median and a top-quartile print, and it comes entirely from how a partial stake is treated. Deals that combine a minority or majority stake with an enterprise value figure need checking before they go into a comparable set. The same caution applies to development-heavy transactions such as Exus's purchase of the NMRD solar joint venture in New Mexico, where most of the capacity was not yet running.
For a buyer such as Plenitude, paying near the top of the range for operating, contracted capacity is a way to add megawatts without taking on development or construction risk.
Frequently asked questions
How much did Plenitude pay for EDP's US solar portfolio? The transaction carried a $400 million enterprise value for an 80 percent stake in the 339.9 MW portfolio. It was announced on 4 January 2024 and completed on 15 February 2024.
What price per MW did the EDP to Plenitude deal achieve? Leap prices it at $1.47 million per MW after grossing the 80 percent stake up to 100 percent. Without that adjustment the figure is $1.18 million per MW.
Which projects did EDP sell to Plenitude? The 240 MW Cattlemen solar park in Texas and the 50 MW Timber Road and 49.9 MW Blue Harvest solar parks in Ohio.
Ready to get deal-ready answers in seconds? Try Enerdatics Leap AI and access verified intelligence across M&A, financings, PPAs, projects, and energy market developments through natural language.