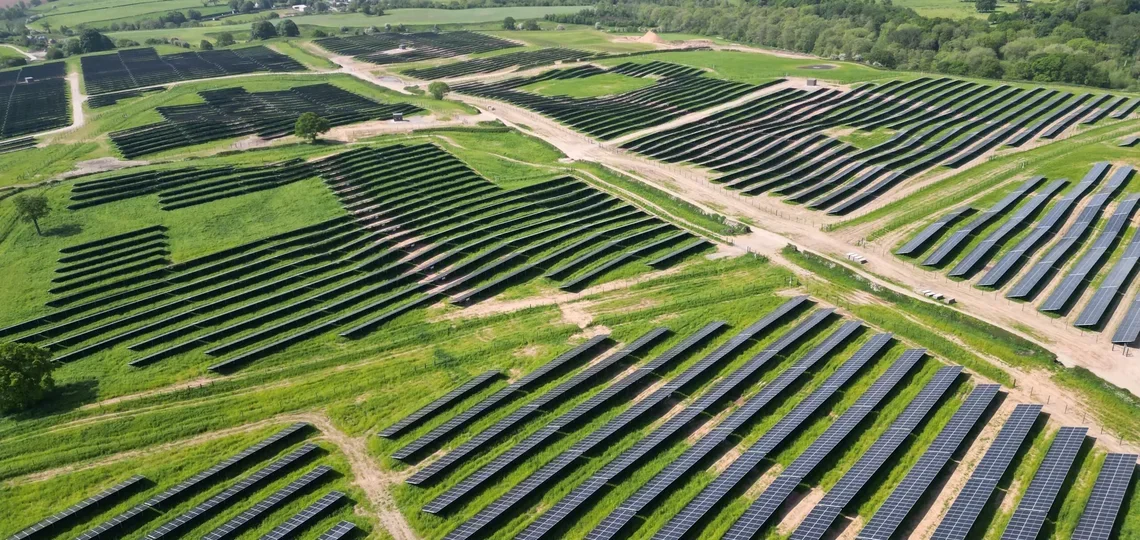
Macquarie Asset Management has sold another tenth of East Anglia ONE, the 714 MW wind farm off the Suffolk coast, to NTR and the Development Bank of Japan. It is the third time Macquarie has changed its position in the project in five years. On paper the deal looks small. Grossed up to the whole wind farm, the price is anything but.
Key takeaways
- Macquarie Asset Management announced on 1 May 2024 the sale of a 10 percent stake in the 714 MW East Anglia ONE offshore wind farm in the UK to NTR, acting for the L&G NTR Clean Power (Europe) Fund, and the Development Bank of Japan.
- The parties did not disclose a price; Enerdatics records a value of $535 million for the 10 percent stake, which implies about $7.49 million per MW for 100 percent of East Anglia ONE.
- East Anglia ONE holds a 15-year inflation-indexed Contract for Difference awarded by the UK Government in 2015 at a tariff of $149 per MWh, and has operated since 2020.
- Macquarie bought 40 percent of East Anglia ONE from Iberdrola in 2019, sold 20 percent to TRIG and InfraRed Capital in 2020, and keeps 10 percent after the sale to NTR and the Development Bank of Japan.
- Across nine operational UK offshore wind stake sales announced between January 2023 and June 2025 where Enerdatics records both a value and the share sold, the grossed-up price ranges from $3.31 million to $8.00 million per MW, with a median of $5.75 million per MW.
How has Macquarie's stake in East Anglia ONE changed since 2019?
Macquarie has been selling down a position it built before the wind farm was finished. It bought 40 percent from Iberdrola in 2019 and supported East Anglia ONE through construction alongside Iberdrola's ScottishPower Renewables, which developed the project. Once the farm was fully running in 2020, Macquarie sold half of that holding to TRIG and InfraRed Capital.
This sale halves what was left. After it, Macquarie Asset Management keeps a single 10 percent interest, the same size as the slice it has just sold.
The buyers are long-term holders rather than builders. NTR bought on behalf of the L&G NTR Clean Power (Europe) Fund, a joint partnership between NTR and Legal & General Investment Management. The Development Bank of Japan came in alongside it. Neither is buying a development story. They are buying a running wind farm with a long contract and debt that pays itself down.
Why does a 10 percent stake price at $7.49 million per MW?
Because a per MW figure only means something when it is measured against the share actually bought. Enerdatics' structured record for the deal shows $0.75 million per MW, which divides the $535 million by all 714 MW. That is the right arithmetic for a whole wind farm and the wrong arithmetic for a tenth of one.
The stake carries 71.4 MW of attributable capacity. Divide the recorded value by that figure and the price rises tenfold, to about $7.49 million per MW. That is the number that can be compared with other deals, and it is high. It is not a market-low print on a cheap stake. It is one of the most expensive operating offshore wind stakes recorded in the UK in this period.
Grossing up is simply the step of converting a stake price into the price it implies for 100 percent of the asset. Without it, every minority deal looks like a bargain.
What is a buyer of East Anglia ONE actually paying for?
Mostly a contract. A Contract for Difference, or CfD, is a UK subsidy in which the generator receives a fixed strike price for its power: when market prices fall below it, the government counterparty pays the difference, and when they rise above it, the generator pays back. East Anglia ONE won its CfD in 2015 at $149 per MWh. The contract runs for 15 years and is indexed to inflation.
That strike price was set in an earlier round, when offshore wind costs were far higher than they became. A buyer of the stake is therefore buying revenue fixed at an early-round tariff that rises with inflation, with no exposure to wholesale price falls for the remaining life of the contract.
The debt structure points the same way. ScottishPower Renewables arranged $3.4 billion of debt to build the site. The facility is fixed rate and fully amortised within the subsidy period. In plain terms, the loan is repaid while the CfD is still paying, so the wind farm's years after the subsidy are expected to be debt free. An equity holder gets contracted cash flow now and an unlevered asset later.
East Anglia ONE sits 43 km offshore and runs 102 Siemens Gamesa turbines of 7 MW each.
Enerdatics' data shows nine operational UK offshore wind stake sales between January 2023 and June 2025 where both a value and the share sold are recorded. Grossed up to 100 percent, they run from $3.31 million per MW for BlackRock's stake in Lynn and Inner Dowsing to $8.00 million per MW for the 12.5 percent of Walney Extension bought by Octopus Energy. The median is $5.75 million per MW, set by Norges Bank's 37.5 percent of Race Bank. East Anglia ONE, at $7.49 million per MW, ranks second of the nine, ahead of Orsted's sales in West of Duddon Sands at $6.39 million and London Array at $5.85 million.
What does the deal signal for UK offshore wind?
It suggests that operating offshore wind with an early, inflation-linked CfD trades at a clear premium to the rest of the operating market. East Anglia ONE's advantage is visible in its contract terms rather than its turbines. A tariff of $149 per MWh on a fully amortising debt package is a different product from a merchant tail or a later, cheaper CfD.
The deal also shows who is setting those prices. Specialist funds like NTR's, pension-backed vehicles and state-linked lenders such as the Development Bank of Japan are now the natural end owners of operating UK offshore wind. Utilities develop and build; infrastructure funds take construction risk; long-duration capital buys the finished asset in slices. Developers working on newer projects are in a different market altogether, as the price Masdar paid for Dogger Bank South shows.
The size of the slice matters too. A 10 percent interest is small enough to fit a single fund's allocation and large enough to carry meaningful cash flow. Macquarie keeping an equal 10 percent leaves it with a continuing interest in how East Anglia ONE performs, and with one more slice it could choose to sell later. Iberdrola's later work in the same waters, including the Amazon contract at East Anglia 3, shows how much commercial activity now clusters off this stretch of coast.
Frequently asked questions
Who bought the East Anglia ONE stake from Macquarie? NTR, acting on behalf of the L&G NTR Clean Power (Europe) Fund, and the Development Bank of Japan bought the 10 percent stake, announced on 1 May 2024.
How much was the East Anglia ONE stake worth? The parties did not disclose a price. Enerdatics records a value of $535 million for the 10 percent stake, equal to about $7.49 million per MW when grossed up to the full 714 MW wind farm.
Does Macquarie still own part of East Anglia ONE? Yes. After the sale, Macquarie Asset Management keeps a 10 percent stake in East Anglia ONE, having held 40 percent in 2019 and 20 percent after its 2020 sale to TRIG and InfraRed Capital.
Ready to get deal-ready answers in seconds? Try Enerdatics Leap AI and access verified intelligence across M&A, financings, PPAs, projects, and energy market developments through natural language.