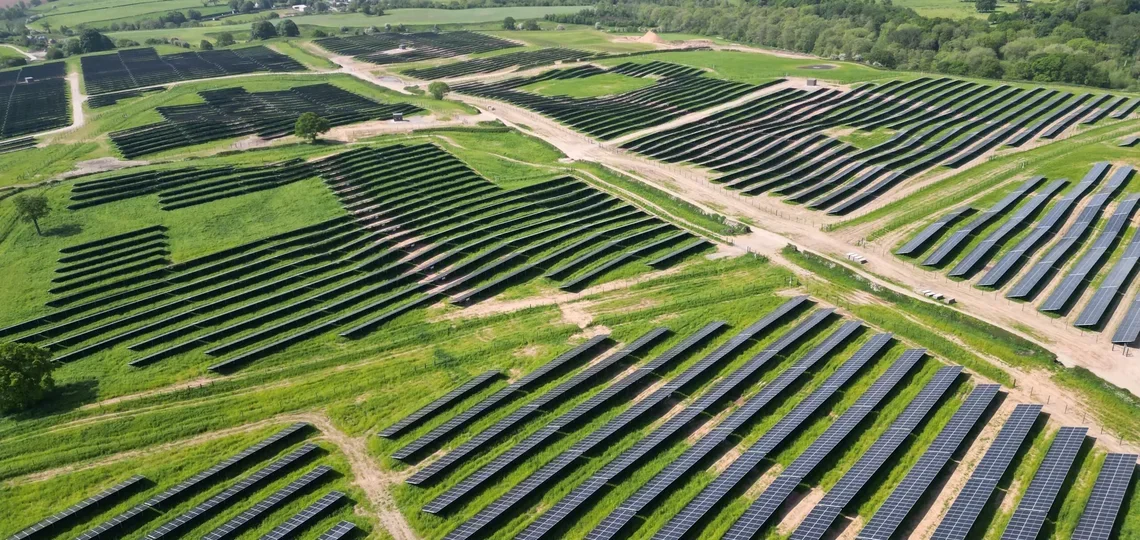
ib vogt has closed about $375 million of project debt for three solar plants clustered around Segovia in central Spain. On its 418 MWdc figure, that is about $0.90 million of debt per MW. Spain's larger solar loans of the same period borrowed noticeably less per MW, and the reason sits in the contracts behind these three plants.
Key takeaways
- ib vogt reached financial close on about $375 million of project finance debt for a 360 MWac / 418 MWdc solar PV portfolio around Segovia, in Castile and Leon, Spain, announced on 15 February 2024.
- The ib vogt portfolio comprises three plants, Serbal (145 MW), Castano (105 MW) and Pato (110 MW), with Serbal and Castano due to operate in December 2024 and Pato in the first quarter of 2025.
- NORD/LB, Santander CIB and BBVA each acted as mandated lead arranger and hedge provider on the ib vogt loan; NORD/LB and BBVA also issued letters of credit and Santander CIB acted as agent.
- All three Segovia plants hold long-term, pay-as-produced, fixed-price PPAs with investment-grade offtakers and are expected to produce a combined 828 GWh a year.
- Enerdatics records 27 debt financings for Spanish solar announced between July 2023 and December 2024; at about $0.90 million per MWdc, the ib vogt loan carries more debt per MW than any other in the set covering more than 100 MW.
Why do these three plants support so much debt?
Because their revenue is fixed before they are built. Each plant has a long-term power purchase agreement on pay-as-produced, fixed-price terms with an investment-grade buyer. Pay-as-produced means the buyer takes whatever the plant generates, hour by hour, at an agreed price. The plant carries the risk of a cloudy year but not the risk of a falling power price.
Lenders size project debt on the cash flow they can rely on. A fixed price paid by a creditworthy buyer is the most reliable cash flow a solar plant can have. Revenue that moves with the wholesale price has to be assumed lower to be safe, so a contracted plant can usually carry a larger loan per MW than one selling into the market.
The plants are also built to produce a lot. They use bifacial modules, which capture light on both faces, and single-axis trackers, which turn the panels to follow the sun. The record gives combined output of 828 GWh a year. Against 418 MWdc of panels, that is close to 2,000 kWh per kW of installed capacity. More output per MW means more contracted revenue per MW, and more debt that revenue can service.
Which MW figure is the right one to use?
That depends on what is being compared, and the record carries three. The DC figure, 418 MW, measures the solar panels. The AC figure measures the inverters that feed the grid. The record's headline gives 365 MWac, while its asset details give 360 MWac, which is also the sum of Serbal, Castano and Pato.
The gap between AC and DC is deliberate. Developers install more panel capacity than inverter capacity, here about 16 percent more, so the plant reaches full export for more of the day. It means the same loan can look quite different per MW. Measured against 418 MWdc, $375 million is about $0.90 million per MW. Measured against 360 MWac, it is about $1.04 million per MW. Per unit of expected output it is about $0.45 million for each GWh of annual generation.
Who lent, and what else did the banks provide?
Three banks, each in more than one role. NORD/LB was mandated lead arranger, letter of credit issuing bank and hedge provider. Santander CIB was mandated lead arranger, agent and hedge provider. BBVA was mandated lead arranger, letter of credit issuing bank and hedge provider. Clifford Chance advised ib vogt on the financing.
A hedge provider fixes the cost of a floating rate exposure, typically interest, for the borrower. A letter of credit issuing bank provides guarantees that a project often has to post to grid operators or offtakers. Packing these roles into the same three lenders keeps the financing in one group of banks with a single view of the project.
Enerdatics records 27 debt financings for Spanish solar announced between July 2023 and December 2024, and 25 of them carry a disclosed amount. Ten others name a capacity that allows a per MW comparison, although the records mix AC, DC and unspecified megawatts, so the comparison is indicative. BRUC's $606.6 million for 842 MW in April 2024 works out at about $0.72 million per MW. Vinci's Cobra IS raised $739.5 million for 1.2 GWp in October 2023, about $0.62 million per MW. Alantra and Solarig's $231.8 million for 306 MW in January 2024 is about $0.76 million, and Matrix Renewables' $190.7 million for 239 MW in April 2024 about $0.80 million. Qualitas Energy's $302.2 million refinancing of the 494 MW Mula plant comes to about $0.61 million. Only one loan in the set beats ib vogt's $0.90 million per MWdc: Matrix Renewables' $50.7 million for a single 50 MW plant, at about $1.01 million.
What does the ib vogt loan signal for Spanish solar financing?
It shows lenders paying for certainty. Spanish solar debt in this period ranged widely per MW, and the larger portfolios borrowed less per MW than ib vogt's three contracted plants. Scale did not buy leverage. Contracted, high-yielding plants did.
It also sits within a run of ib vogt financings in Spain. About seven weeks later Leap records a separate $64.5 million loan from Banco Santander for ib vogt's Baobab project, a plant ib vogt later agreed to sell, as covered in ib vogt's Baobab sale to EOS Holding. Spanish portfolios with secure revenue have drawn equity buyers as well as lenders, as the 49 percent stake in Bruc's Spanish solar portfolio showed.
The question the record leaves open is price. The PPAs are fixed, but neither their tariffs nor the offtakers are named, so the revenue that supports $375 million of debt cannot be checked from outside.
Frequently asked questions
How much debt did ib vogt raise for its Segovia solar portfolio?About $375 million of project finance debt, announced on 15 February 2024, from NORD/LB, Santander CIB and BBVA.
Which solar plants does the ib vogt loan finance?Serbal (145 MW), Castano (105 MW) and Pato (110 MW), three plants clustered around Segovia in Castile and Leon. Together they total 360 MWac and 418 MWdc.
When will the ib vogt Segovia plants start operating?Serbal and Castano were slated for commercial operation in December 2024, and Pato was expected to be fully operational in the first quarter of 2025.
Ready to get deal-ready answers in seconds? Try Enerdatics Leap AI and access verified intelligence across M&A, financings, PPAs, projects, and energy market developments through natural language.