energyRe has raised $815 million to finish five solar farms in South Carolina. Duke Energy is the buyer of the power on every one of them. On two of the five, Duke is not really the buyer at all, and the contracts on those two run ten years shorter than the headline.
Key takeaways
- energyRe has secured $815 million from a consortium of banks and investors for the construction of five utility-scale solar projects in South Carolina with a combined capacity of 466.3 MW, equal to about $1.75 million per MW.
- The package combines a debt facility and a tax equity facility, with Bank of America acting as documentation agent alongside Canadian Imperial Bank of Commerce and Santander Bank.
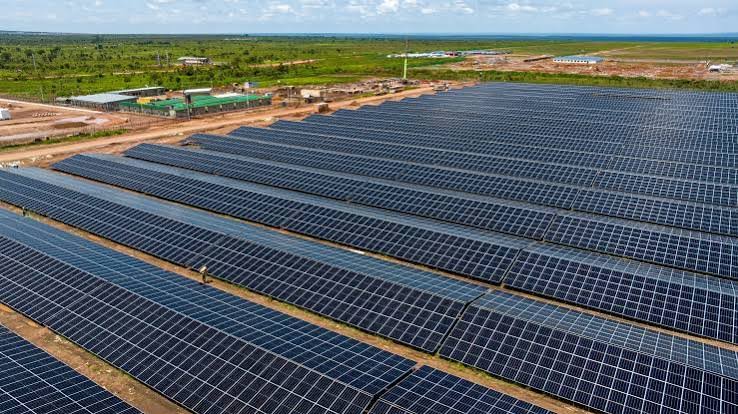
- The portfolio comprises Ross Solar at 75 MW, Shorthorn Solar at 85.46 MW, Rollins Solar at 105.42 MW, Culpepper Solar at 105.42 MW and Clarendon Solar at 95 MW, all under construction and expected to be operational by the end of 2027.
- Shorthorn and Culpepper, together 190.88 MW or 40.9 percent of the portfolio, sit on 15-year Duke Energy PPAs backed by parallel 15-year offtake agreements with the US Department of Defense through Duke's Green Source Advantage framework.
- Enerdatics records 456 US solar financings since the start of 2024, of which 202 are at or above $200 million. energyRe states it has now raised more than $1.9 billion in total.
What does the US Department of Defense have to do with a South Carolina solar farm?
It is the party consuming the power on two of the five projects, without being the party that signed the generation contract. Duke Energy's Green Source Advantage framework is a utility programme that lets a large customer procure renewable generation from a third-party developer while the utility sits in the middle, buying from the project and delivering to the customer. On Shorthorn and Culpepper, energyRe holds 15-year PPAs with Duke, and Duke holds parallel 15-year offtake agreements with the Department of Defense. The developer's counterparty risk is a regulated utility. The demand driving the contract is federal.
That structure matters to a lender in a way a simple corporate PPA does not. A bank underwriting Shorthorn is taking Duke Energy credit for 15 years, which is investment grade and well understood. It is not taking US government credit, and it is not taking the risk that a corporate offtaker is downgraded or acquired. The federal agreement sits one step behind the one being financed, which is why the financing could be structured with a tax equity facility alongside the debt rather than as a more conservative debt-only package.
Why do two PPA tenors sit inside one portfolio?
Because the five projects were contracted through two different routes. Enerdatics' record states that long-term revenue across the solar facilities is secured through 25-year power purchase agreements with Duke Energy, and separately that Shorthorn and Culpepper carry 15-year Duke PPAs backed by the Department of Defense arrangements. Enerdatics also records an earlier energyRe agreement with Duke, announced in February 2026, covering 360 MW at 25 years.
The practical effect is a portfolio with two revenue horizons. Shorthorn and Culpepper are 190.88 MW of the 466.3 MW total, or 40.9 percent. On those, contracted revenue ends after 15 years and the assets face the merchant market or a recontracting decision at a point when the rest of the portfolio still has a decade of fixed price left. Anyone reading "25-year PPAs with Duke Energy" as a description of the whole 466 MW is reading it too broadly. For a lender this is ordinary: debt is sized to the weakest contracted tail in the pool. For anyone valuing the equity, the blended contract life is the number that matters, and it is shorter than the headline implies.
Is $815 million a lot for 466 MW?
It works out at about $1.75 million per MW, and the figure covers more than a construction loan. The package is a hybrid of debt and tax equity, so it blends borrowed money with an investor monetising federal tax credits, and the total therefore sits closer to full project cost than a debt facility alone would. Comparing it with a pure debt raise understates how much of the capital stack it represents.
Against the market the size is substantial but not exceptional. Enerdatics records 456 US solar financings since the start of 2024, of which 202 are at or above $200 million, so nine-figure solar packages are routine. The ones materially larger than this are mostly multi-gigawatt or multi-state: Cypress Creek's roughly $3.5 billion for the Steel River portfolio in June 2026, IPX Power's roughly $4.95 billion for the 2.75 GW Darden project in May 2026, and Enlight's roughly $2.62 billion for the CO Bar complex in June 2026. Among single-state construction packages, energyRe's is at the top end. The record also describes it as among the largest solar-only project financings ever closed in South Carolina, which is the company's framing rather than an Enerdatics calculation.
Enerdatics records that energyRe has raised more than $1.9 billion in total, and this is not its first South Carolina package. In November 2025 the company closed a $370 million financing for a South Carolina solar portfolio structured and arranged by Santander, with Bank of America, Natixis and Societe Generale participating. Santander and Bank of America appear again in this one. Within the wider US market, per-MW borrowing varies more than headline sizes suggest, as the gap between Zelestra's Indiana and Texas solar debt showed in October 2026. energyRe's equity base was set in December 2023, when Glentra Capital, Novo Holdings and PKA anchored a $300 million consortium investment.
What does the deal signal for US solar?
The deal signals that utility-intermediated procurement is doing work that corporate PPAs cannot. A federal agency wanting renewable power at a specific scale and location has limited appetite for 25-year merchant-adjacent contracts, and a developer has limited appetite for federal contracting risk. Routing both through a regulated utility's green tariff programme gives the agency the product and the developer a bankable counterparty. Expect more of this where the ultimate buyer is a government body rather than a hyperscaler.
The second signal concerns South Carolina. energyRe states a goal of investing $2 billion in the state by 2030, and these five projects plus the 2025 package put it a long way down that path. South Carolina is not a market that features in most US solar league tables, and a single sponsor concentrating this much capital in one regulated utility territory is a bet on that utility's procurement continuing. The tenor split inside the portfolio is the hedge against it not doing so.
Frequently asked questions
How much has energyRe raised for its South Carolina solar portfolio?$815 million from a consortium of banks and investors for five projects totalling 466.3 MW, equal to about $1.75 million per MW. The package combines a debt facility and a tax equity facility, with Bank of America as documentation agent alongside CIBC and Santander Bank.
Who buys the power from the five projects?Duke Energy. Shorthorn and Culpepper sit on 15-year Duke PPAs backed by parallel 15-year offtake agreements with the US Department of Defense, delivered through Duke's Green Source Advantage framework. Enerdatics' record describes 25-year Duke PPAs across the solar facilities.
When will the projects be operational?All five are under construction and the portfolio is expected to be operational by the end of 2027. The projects are Ross, Shorthorn, Rollins, Culpepper and Clarendon, located in Darlington, Lee and Clarendon counties.
Ready to get deal-ready answers in seconds? Try Enerdatics Leap AI and access verified intelligence across M&A, financings, PPAs, projects and energy market developments through natural language.