Foresight Group has bought into a 1.8 GW project in the Scottish Highlands that will not generate a unit of power until 2033. The headline capacity makes it sound like a large wind farm. It is not. The number that decides what Earba is worth does not appear in the deal headline at all.
Key takeaways
- Foresight Energy Infrastructure Partners II acquired a stake in the Earba pumped storage hydro project in the Scottish Highlands from Gilkes Energy on 19 October 2026. Neither the size of the stake nor the consideration was disclosed.
- Earba is rated at 1.8 GW of generating capacity and 40 GWh of storage, which is 22 hours of output at full power.
- Enerdatics records seven pumped storage hydro transactions in Europe since the start of January 2022, and not one of the seven carries a disclosed value.
- Of 57 UK battery storage transactions Enerdatics records since the start of January 2024, 24 state a duration. The median of those 24 is two hours and the longest is five hours.
- Earba qualified under Track 2 of Ofgem's cap and floor scheme for long duration electricity storage in September 2025 and was included in the regulator's 2026 minded-to decision, with a final decision expected in autumn 2026.
What does 1.8 GW actually buy at Earba?
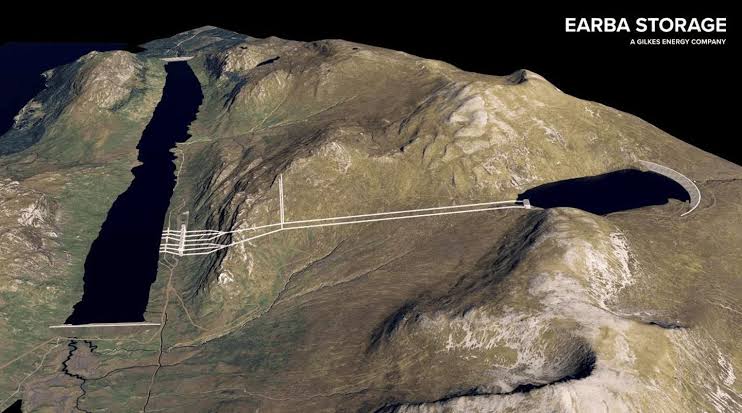
It buys 40 GWh. Pumped storage hydro moves water between two reservoirs at different heights, pumping it uphill when power is cheap and releasing it back through turbines when power is needed. The power rating tells you how fast the asset can deliver. The energy capacity tells you how much it can deliver before the upper reservoir empties.
Those two numbers are independent, and at Earba the ratio between them is the whole story. Running the figures above gives 22 hours at full output. A grid battery is built to cover a short evening peak. An asset that holds full output for most of a day covers a still, dark winter night.
The engineering explains why the energy number is so large. Earba uses two existing lochs, Lochan na h-Earba as the lower reservoir and Loch a' Bhealaich Leamhain as the upper, with dams raising their water levels. The upper reservoir alone will hold around 55 million cubic metres. The build also involves three dams, up to three headrace tunnels, a powerhouse, a switchyard and two aqueducts. Once operating, the project is expected to generate enough electricity to power more than 1.4 million UK homes on average.
The regulatory work is largely behind it. Earba received consent under Section 36 of the Electricity Act 1989 in March 2025, the approval the UK requires before a large generating station can be built, and Enerdatics classifies it as the UK's largest consented long duration energy storage project. Construction is expected to take five to six years, with commercial operations in 2033.
Why does a cap and floor change the maths?
Because it removes the question that makes a 2033 asset unfinanceable today. Ofgem's cap and floor scheme for long duration electricity storage provides revenue support when earnings fall below a specified floor, and requires revenues above a specified cap to be repaid to the regulator. The floor moves downside risk away from the investor. The cap moves the upside to consumers.
For an asset of this shape, that trade is the point. Earba is a civil engineering project with no revenue until the next decade. Merchant arbitrage spreads in 2033 cannot be underwritten from 2026, and lenders will not size debt against a number nobody can forecast. A floor converts an unknowable revenue line into a modellable one, which is what allows construction capital to be committed at all.
The framework is not finished. Earba qualified under Track 2 of the scheme in September 2025 and was then included in Ofgem's 2026 minded-to decision, with the final decision expected in autumn 2026. Foresight has therefore committed capital to the next phase of development while the revenue mechanism that justifies the project is still in draft. That is a familiar pattern here. Statkraft bought the consented Red John scheme near Inverness in December 2023 and said at the time that it was looking forward to the UK government providing support mechanisms for it.
Why is Gilkes Energy bringing in a partner rather than building alone?
Because the capital needed at this stage is a different order of magnitude from development spend. Gilkes Energy, a subsidiary of Gilbert Gilkes and Gordon, took Earba through consent. Foresight's money now funds detailed engineering, procurement, site investigations and construction preparations, with Gilkes continuing alongside its existing delivery partners. LCP Delta advised Gilkes. This is the second time Gilkes has done exactly this: in July 2024 it formed a joint venture with SSE to develop the roughly 1.8 GW Fearna scheme in Scotland. The same developer now holds two schemes of nearly identical scale, each advanced with a large external counterparty rather than from its own balance sheet.
For Foresight the logic runs the other way. The buyer is Foresight Energy Infrastructure Partners II, the same fund that backed German battery developer Mirai Power in March 2026 as part of an ambition to build a pan-European independent flexibility provider. Short duration batteries and a 22 hour scheme solve different problems on the same grid, and a flexibility platform that owns only one of them is half built.
Enerdatics records seven pumped storage hydro transactions in Europe since the start of January 2022, and not one carries a disclosed value. Four of the seven involve British assets: Earba, Statkraft's purchase of Red John, the SSE and Gilkes joint venture on Fearna, and CDPQ's agreement to buy a 25 percent stake in First Hydro Company, owner of 2,088 MW of operating UK pumped storage, from Brookfield in September 2024. The other three cover Spain and Germany. A buyer pricing a consented UK pumped storage scheme is working without a single public comparable.
What does the deal signal for UK long duration storage?
It shows capital arriving ahead of the final rules rather than after them. Consented pumped storage sites cannot be manufactured: they need two bodies of water at different heights, in the right geology, with a grid connection and a planning consent. Once a revenue framework is settled, the schemes that already hold consent are the only ones that can move quickly, and the queue to buy into them will be longer than it is now.
The absence of price discovery is the other half of the picture. Seven European transactions since 2022 with no disclosed value means each is negotiated on its own engineering and its own assumed revenue model. The cap and floor may be what ends that. A scheme with a defined floor has a revenue line two parties can model from the same starting point, and that is the precondition for a market where these stakes trade at observable prices. The autumn 2026 final decision is the thing to watch.
Frequently asked questions
Who sold the Earba stake, and what did it fetch?Gilkes Energy, a subsidiary of Gilbert Gilkes and Gordon, sold to Foresight Energy Infrastructure Partners II. Neither the stake size nor the consideration was disclosed. LCP Delta advised Gilkes Energy.
How long can Earba run at full output?Around 22 hours. The project is rated at 1.8 GW of generating capacity against 40 GWh of storage.
When will Earba start generating electricity?Commercial operations are expected in 2033. The project received Section 36 consent in March 2025 and construction is expected to take around five to six years.
Ready to get deal-ready answers in seconds? Try Enerdatics Leap AI and access verified intelligence across M&A, financings, PPAs, projects, and energy market developments through natural language.